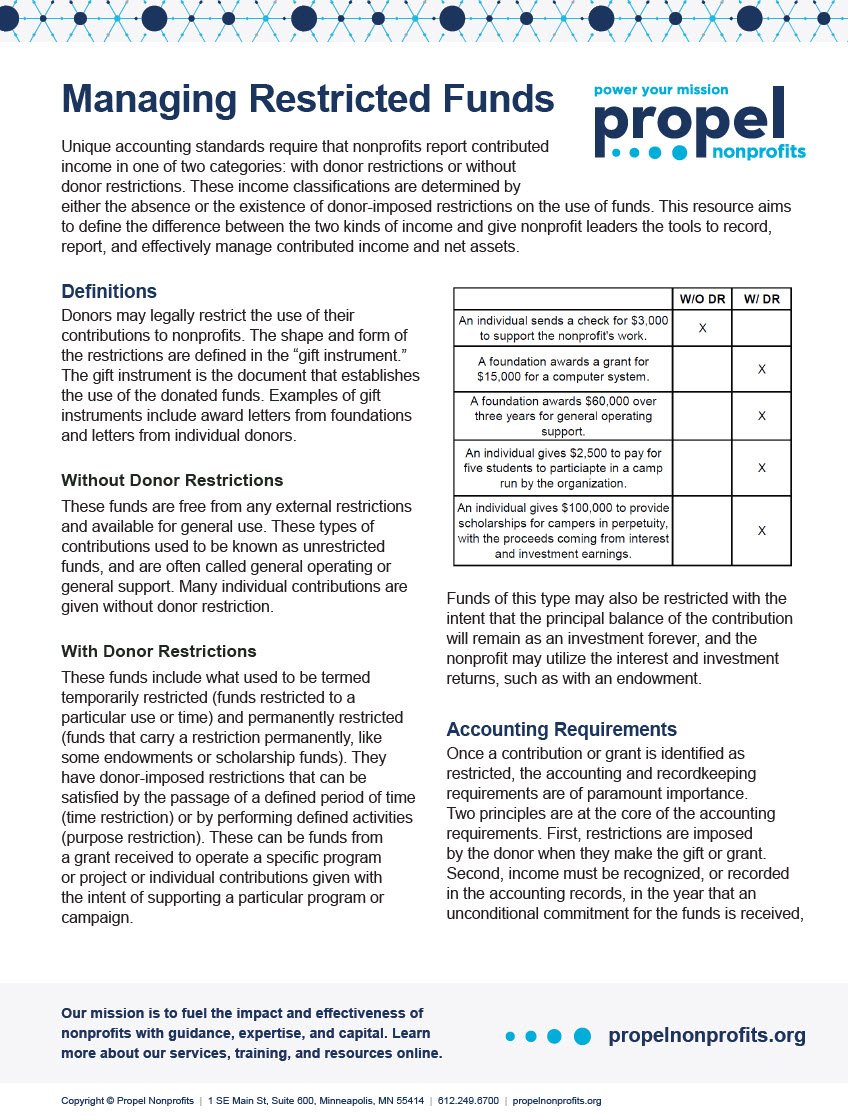
Unique accounting standards require that nonprofits report contributed income in one of two categories: with donor restrictions or without donor restrictions.

 Financial Aspects of Strategic Planning NAHC-
 Working with Financial Statement
 What Are Patronage Refunds
 Understanding Cooperative Bookkeeping and Financial
 Managing Your Cooperative Equity
 Income Tax Treatment of Cooperatives
 Income Tax Treatment of Cooperatives – Handling of Losses
 Income Tax Treatment of Cooperative Patronage Refunds
 Impact of Tax Reform on Agricultural Cooperatives
 Financing Cooperative & Mutual Housing.